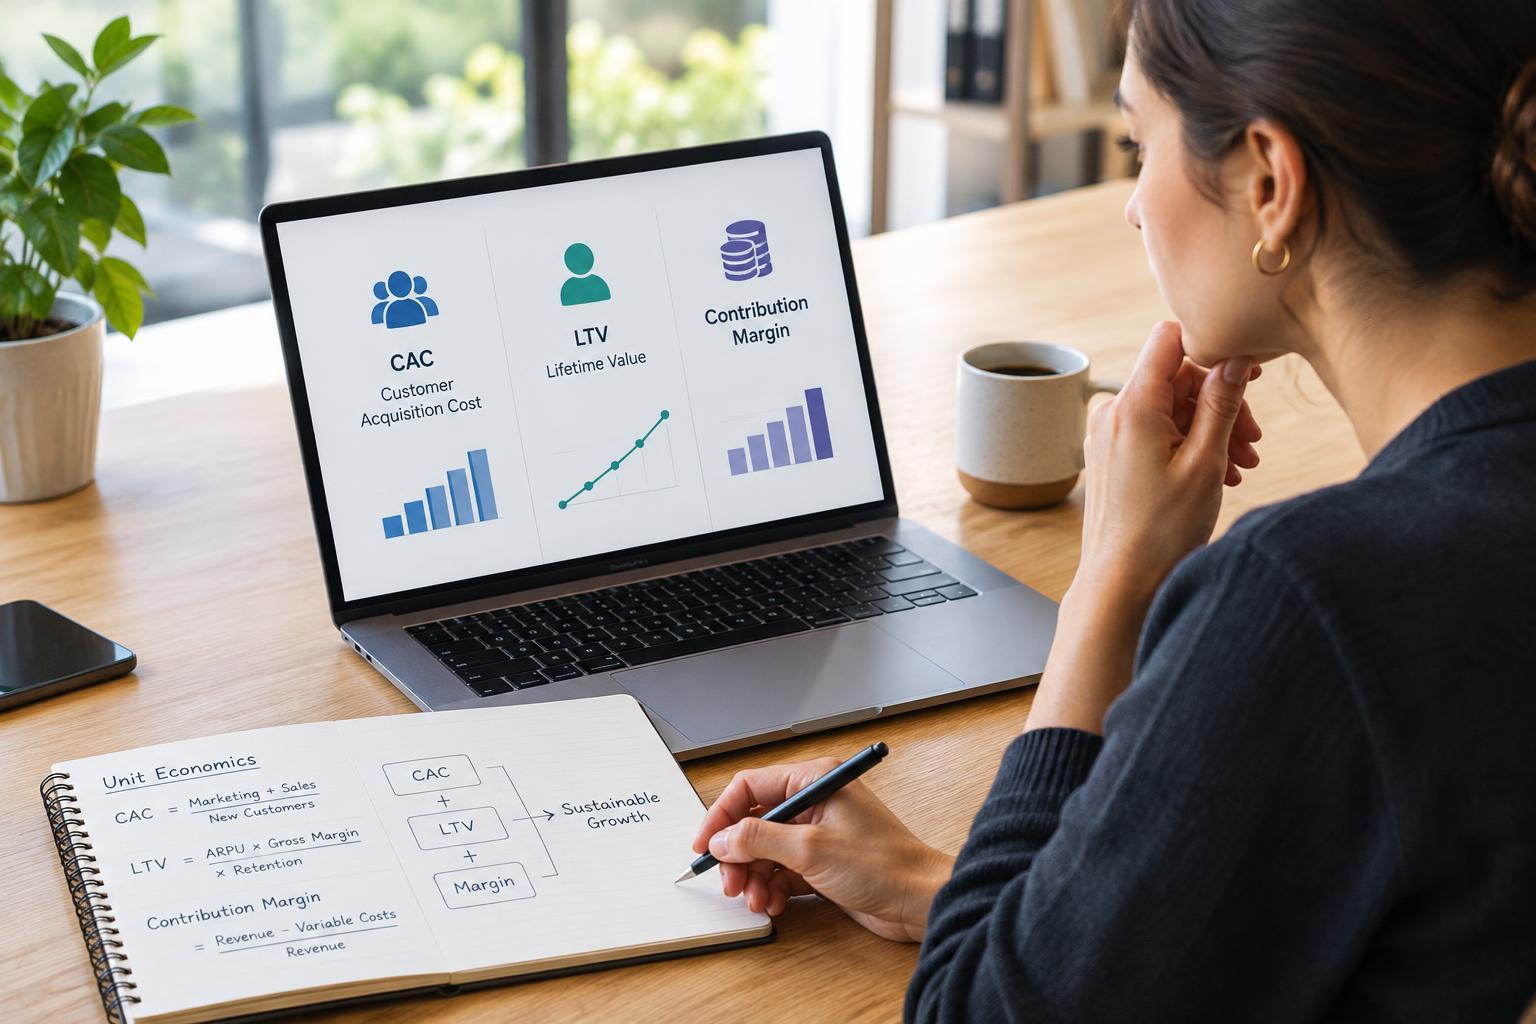
1. Start with the economics of one customer
Unit economics describes the revenue and costs associated with a single unit of business activity. That unit might be an order, a subscription, or a customer relationship. For customer-focused analysis, three measures are especially useful: customer acquisition cost (CAC), contribution margin, and customer lifetime value (LTV). Together, they help answer whether acquiring and serving customers creates enough value to support the wider business.
Choose your unit and time period before collecting numbers. A retailer might calculate contribution per order, then estimate how many orders a customer places. A subscription business might start with contribution per customer per month. Keep these definitions consistent: comparing monthly revenue with annual costs, or individual users with paying company accounts, produces misleading results.
Consider a hypothetical subscription business that charges $50 per customer each month. It spends $12,000 acquiring 100 new paying customers and incurs $20 in monthly variable service costs per customer. We will use these figures throughout. They are illustrative assumptions, not benchmarks for what a business should achieve.
2. Calculate customer acquisition cost
The basic formula is: CAC = acquisition spending divided by new customers acquired. In our example, $12,000 divided by 100 gives a CAC of $120. Count new paying customers rather than leads, free accounts, or website visitors, unless you are deliberately measuring a different stage of the funnel.
The numerator needs a clear definition. Advertising spend alone gives a narrow view. A broader acquisition cost can include relevant sales and marketing salaries, agency fees, commissions, creative production, and acquisition tools. If a team also handles retention or existing accounts, allocate its costs reasonably rather than treating every dollar as acquisition spending. Label ad-only and fully loaded calculations separately.
Timing matters because spending and conversions may happen in different periods. Dividing this month's sales costs by this month's new customers can distort CAC when the sales cycle lasts several months. Where possible, connect spending to the customers it helped acquire. Also examine channels separately: a blended average can hide an expensive campaign behind strong referrals or organic acquisition.
3. Calculate contribution margin before estimating value
Contribution margin is revenue minus the variable costs associated with delivering that revenue. These may include product costs, payment processing, shipping, usage-based infrastructure, and support costs that scale with customer activity. Use revenue after discounts and refunds, and define which costs belong in your model. Some costs rise in steps rather than smoothly, so revisit assumptions as volume changes.
In the example, monthly contribution per customer is $50 minus $20, or $30. The contribution margin percentage is $30 divided by $50, multiplied by 100, which equals 60%. This means each revenue dollar leaves 60 cents to help cover costs outside this calculation, including acquisition and fixed overhead.
Contribution is not net profit. Rent, management salaries, product development, and other overhead may still need to be paid. For the calculations below, keep acquisition spending separate from service costs so CAC is not counted twice. Also avoid automatically substituting accounting gross margin: the costs included in gross margin may differ from those in your contribution model.
4. Estimate customer lifetime value cautiously
For this analysis, LTV means expected lifetime contribution before acquisition costs, not total lifetime revenue. The general formula is: LTV = expected cumulative revenue from a customer minus expected cumulative variable service costs. For a subscription with stable monthly economics, a shortcut is monthly contribution multiplied by expected customer lifetime.
A simplified subscription model estimates average lifetime as one divided by monthly customer churn. If monthly churn is 5%, estimated lifetime is 20 months. At $30 monthly contribution, estimated LTV is $600. This shortcut assumes a reasonably stable churn probability, stable contribution, and no complicated reactivation behavior. It can be unreliable for young businesses or customers whose cancellation patterns change substantially over time.
A stronger approach tracks cohorts: groups of customers acquired during the same period. Measure their retention, purchases, and contribution over time, then clearly separate observed results from forecasts. For non-subscription businesses, estimate repeat purchases and contribution per purchase rather than applying a subscription churn formula. More advanced models also discount future contribution to reflect the delay in receiving it.
5. Read the metrics together and test the assumptions
Our example produces an LTV-to-CAC ratio of $600 divided by $120, or 5. CAC payback is $120 divided by $30 monthly contribution, or four months for a customer who stays active, assuming steady contribution. These figures describe different things: the ratio estimates lifetime acquisition efficiency, while payback indicates how quickly acquisition spending might be recovered. Neither guarantees overall profitability.
Retention makes the forecast sensitive. If monthly churn rises to 10%, the same simplified model gives a ten-month lifetime and $300 LTV. The ratio falls to 2.5 even though price and CAC are unchanged. Compare conservative and optimistic scenarios, inspect cohorts and channels, and monitor actual cash timing. Healthy-looking averages are most useful when their definitions, assumptions, and limitations remain visible.


