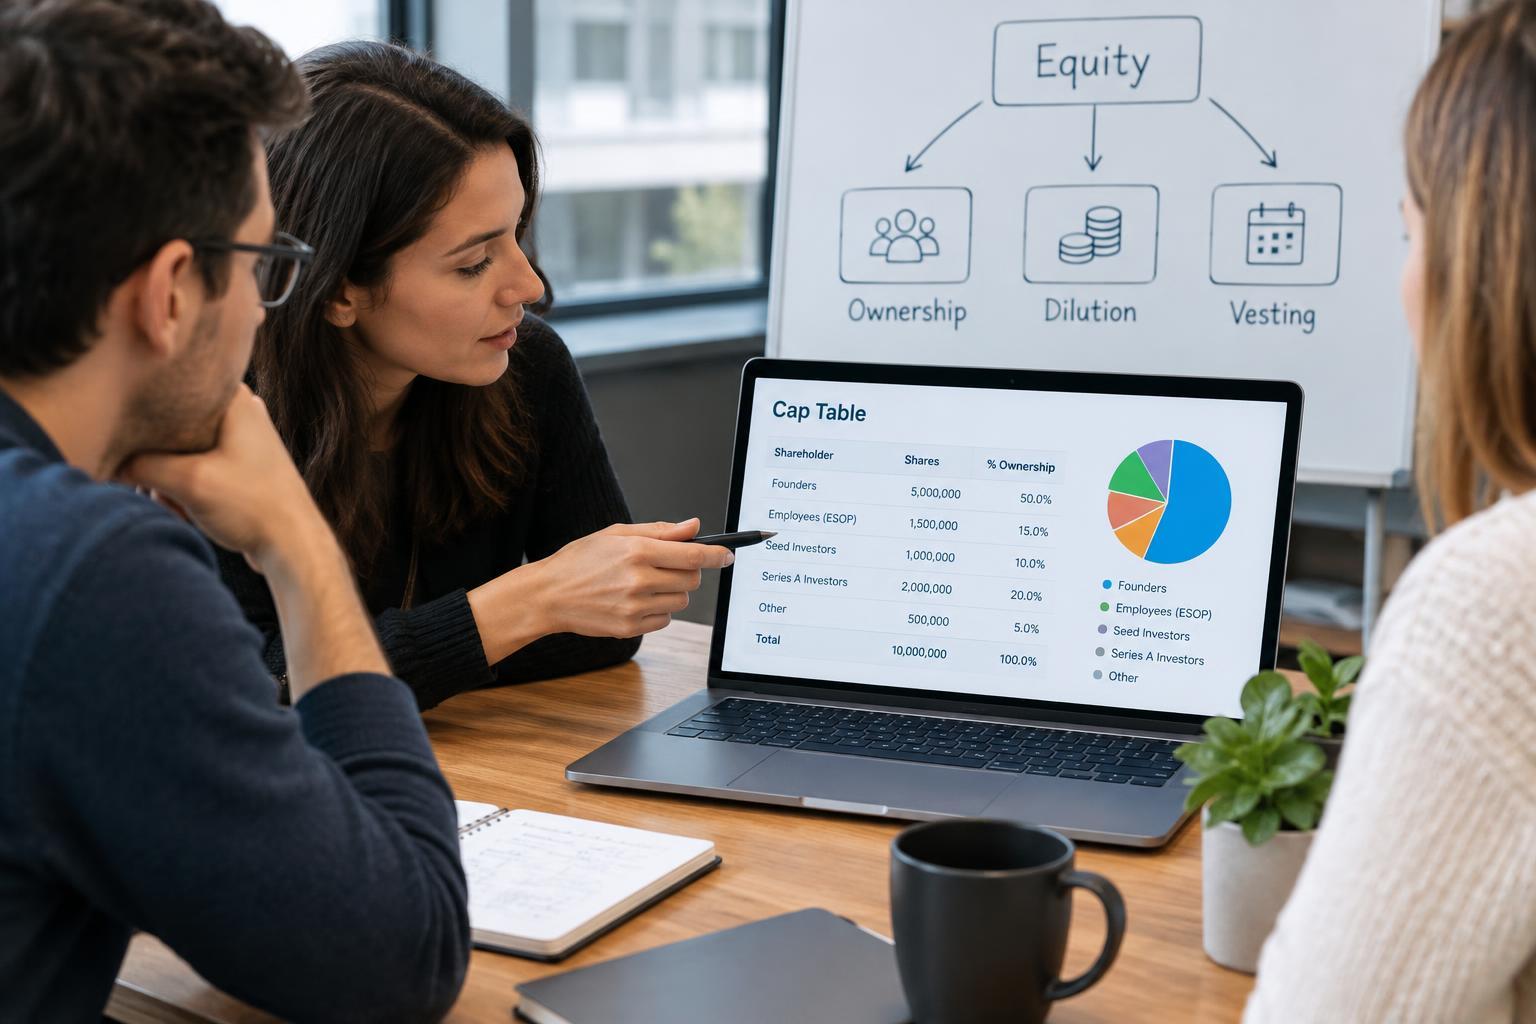
What Startup Equity Actually Represents
Startup equity is an ownership interest in a company, or a contractual right that may lead to ownership. Founders typically receive shares, investors acquire securities in exchange for capital, and employees may receive shares or stock options as part of their compensation. These instruments are related, but they do not all provide the same rights.
A share represents ownership. A stock option generally gives its holder the right to purchase a specified number of shares at an exercise price, subject to conditions and deadlines. Holding an option is therefore not the same as already owning the underlying shares.
Ownership percentage also does not guarantee a matching share of any sale proceeds. Different share classes can have different voting and payout rights. This overview explains the mechanics for general understanding, rather than providing financial, legal, or tax advice.
How to Read a Capitalization Table
A capitalization table, usually called a cap table, records the company's equity ownership. A useful version identifies holders, security types, share counts, and ownership percentages. It may also track option grants, an unallocated option reserve, warrants, and securities that could convert into shares.
The crucial question is what the percentage calculation includes. An outstanding-share view generally counts shares already issued and outstanding. A fully diluted view generally includes additional shares that could arise from options and other instruments, often including the unallocated option reserve. The exact definition should be stated because calculations can differ.
For example, suppose founders hold 8 million shares and the company has reserved 2 million shares for employee options. On a fully diluted basis that includes the entire reserve, founders hold 80% and the option pool represents 20%. The reserve is not a shareholder: it represents potential future ownership. Reading percentages without understanding this denominator can produce misleading comparisons.
How Dilution Changes Ownership Percentages
Dilution occurs when additional equity increases the share count used to calculate ownership. Existing holders can keep exactly the same number of shares while owning a smaller percentage. This commonly happens during fundraising, option-pool increases, or the conversion of earlier financing instruments.
Consider a simplified priced funding round with an $8 million pre-money valuation and $2 million in new investment. The post-money valuation is $10 million, and the new investor receives 20% of the company. Assuming no other changes, existing fully diluted stakes are multiplied by 80%. The founders' 80% stake in the previous example becomes 64%, while the option pool's 20% becomes 16%.
A smaller percentage does not necessarily mean a less valuable holding: financing may help the business grow. However, a funding valuation is not a promise of realizable value. Option-pool increases also matter. If investors require a larger pool before their investment, that increase generally places additional dilution on pre-round holders.
How Vesting Connects Equity to Continued Service
Vesting determines when someone earns the right to keep shares or exercise options under an agreement. A common startup arrangement is four-year vesting with a one-year cliff. In a typical version, nothing vests before the first anniversary, 25% vests at that point, and the rest vests monthly over the following three years.
For a 48,000-option grant under that schedule, 12,000 options would vest at the cliff, followed by 1,000 each month. Leaving before the cliff would generally mean no vested options. Leaving later would normally stop further vesting, while exercising vested options may remain subject to a deadline and other terms.
Founder shares can also be subject to vesting through company repurchase rights over unvested shares. Acceleration provisions may change the schedule after specified events, such as an acquisition combined with a qualifying termination. Vesting, exercise, and the ability to sell are separate milestones; the agreement governs each.
Why Convertibles and Investor Rights Complicate the Picture
Some startups raise money through convertible notes or simple agreements for future equity, known as SAFEs. These can create future dilution even when the investor does not immediately appear as a shareholder. Conversion depends on the instrument's terms and triggering events.
Valuation caps and discounts can affect the price at which these instruments convert. A cap is not necessarily a statement of the company's current value, and different instruments can produce different ownership outcomes. Cap-table projections should therefore show their assumptions explicitly.
Preferred shares can also carry liquidation preferences that affect how proceeds are distributed in a sale. As a result, multiplying an ownership percentage by a headline sale price may not accurately estimate a holder's payout.
Questions That Make Equity Easier to Understand
When reviewing an equity grant, establish the instrument type, number of shares or options, and percentage on a clearly defined basis. Check the vesting start date, cliff, exercise price, expiration rules, and treatment after departure. Ask whether the stated percentage includes the option reserve and outstanding convertible instruments.
For founders, keep the cap table aligned with approved grants and transaction documents. Model fundraising and pool changes before comparing outcomes. For everyone, the central habit is the same: evaluate the share count, denominator, and contractual rights together. A percentage alone tells only part of the ownership story.


