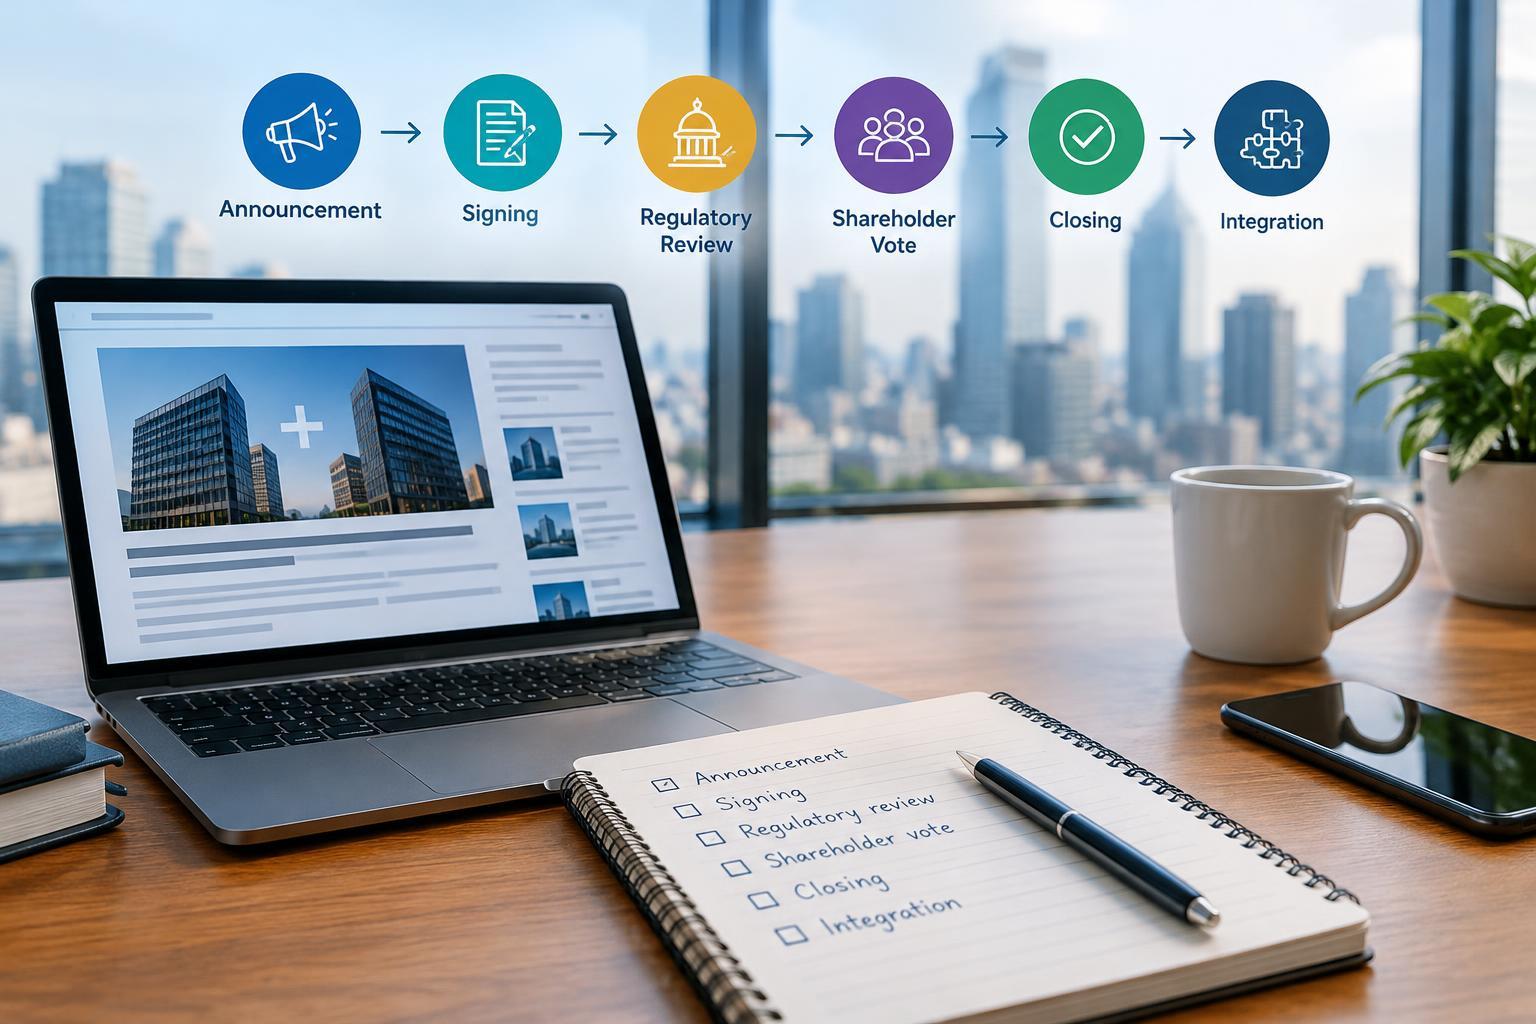
1. Identify What Has Actually Been Announced
Merger headlines often compress several different stages into a few words. A company may be exploring a sale, discussing an offer, signing an agreement, or completing an acquisition. These are not interchangeable events. Before interpreting the business implications, identify the precise action described in the announcement.
Early reports may refer to talks, an unsolicited proposal, or a nonbinding expression of interest. None necessarily means the companies have agreed to a transaction. A definitive agreement is a stronger milestone: the parties have signed terms governing the proposed deal. Even then, closing usually depends on conditions, and the agreement may provide ways for either side to terminate it.
Check what is being purchased. An acquisition of an entire company differs from buying a product line, selected assets, or a minority stake. Also distinguish cash consideration from shares or a combination of both. A headline deal value may include assumed debt or contingent payments, so figures from different reports may not describe the same thing.
2. Map the Conditions Between Signing and Closing
Once an agreement is announced, look for its closing conditions. Depending on the transaction, these can include competition clearance, shareholder approval, sector-specific permissions, or other contractual requirements. Some deals need approvals in several countries. Progress in one jurisdiction does not establish that every condition has been satisfied.
Treat the companies’ expected closing window as an estimate, not a promise. Reviews can take longer than anticipated, requests for information can extend the process, and the parties may amend their agreement. An outside date or termination date is also different from a scheduled closing date: it generally concerns contractual rights if the transaction has not closed by a specified point, subject to the agreement’s terms.
A simple tracking note helps keep the sequence clear. Record the announcement status, required approvals, approvals received, unresolved conditions, and latest expected closing window. Add the publication date of each update. This prevents an older report about pending approval from being mistaken for the deal’s present status.
3. Read Regulatory Reviews as Processes, Not Verdicts
Regulatory review is often the most confusing part of merger coverage. Competition authorities generally examine whether a transaction could harm competition, while other bodies may consider national security or industry-specific requirements. These reviews serve different purposes. Clearance from one authority does not necessarily resolve concerns raised by another.
An extended investigation or request for additional information is not automatically a rejection. It means the authority is examining the transaction more closely under its procedures. Equally, the absence of an immediate objection should not be treated as approval. Look for the authority’s precise decision and whether it is preliminary, final, conditional, or subject to further proceedings.
Some transactions receive clearance with remedies, such as selling a business unit or accepting restrictions on certain conduct. Those obligations can change the commercial shape of the deal. If a challenge reaches court, distinguish the regulator’s position from the court’s ruling and check what that ruling permits. A procedural victory may not settle every remaining issue.
4. Confirm Completion—and Separate It From Integration
Shareholder approval, regulatory clearance, and transaction completion are separate milestones. A vote in favor may satisfy one condition without transferring ownership. To establish that a deal has closed, look for an explicit completion announcement or an applicable formal filing, rather than assuming that the last widely reported approval ended the process.
Even completion can require careful reading. Some transactions close in stages, cover only part of a previously announced package, or leave certain assets outside the purchase. Confirm which entities or assets changed hands and whether any portions remain pending. If reports conflict, compare their timestamps and the scope each one describes.
After closing, integration begins or continues. Combining technology systems, reorganizing teams, aligning products, and changing brands can take much longer than the legal transfer. Statements about expected efficiencies or future product improvements remain plans, not demonstrated outcomes. Customers and suppliers should look for specific notices about contracts, support, billing, or service changes rather than infer them from ownership alone.
5. Build a Reliable Reading Routine
Use reporting to understand context, then check the underlying material when available. Company announcements explain the parties’ stated intentions; regulatory notices describe official review steps; shareholder documents and formal filings may supply transaction details. Each has a different purpose. Company language can emphasize benefits, while a short news report may omit conditions that matter.
For every update, ask four questions: What changed? Who confirmed it? Which conditions remain? Does this alter the scope or timing of the deal? Keep confirmed facts separate from management expectations, analyst interpretations, and unattributed speculation. Several articles repeating the same original report do not necessarily provide independent confirmation.
Finally, allow for outcomes other than completion. Deals can be revised, replaced by competing offers, or abandoned. Follow the latest explicit status rather than the original headline. Reading merger news as a sequence of documented milestones makes it easier to understand business developments without confusing an intention, an approval, and a finished transaction.


