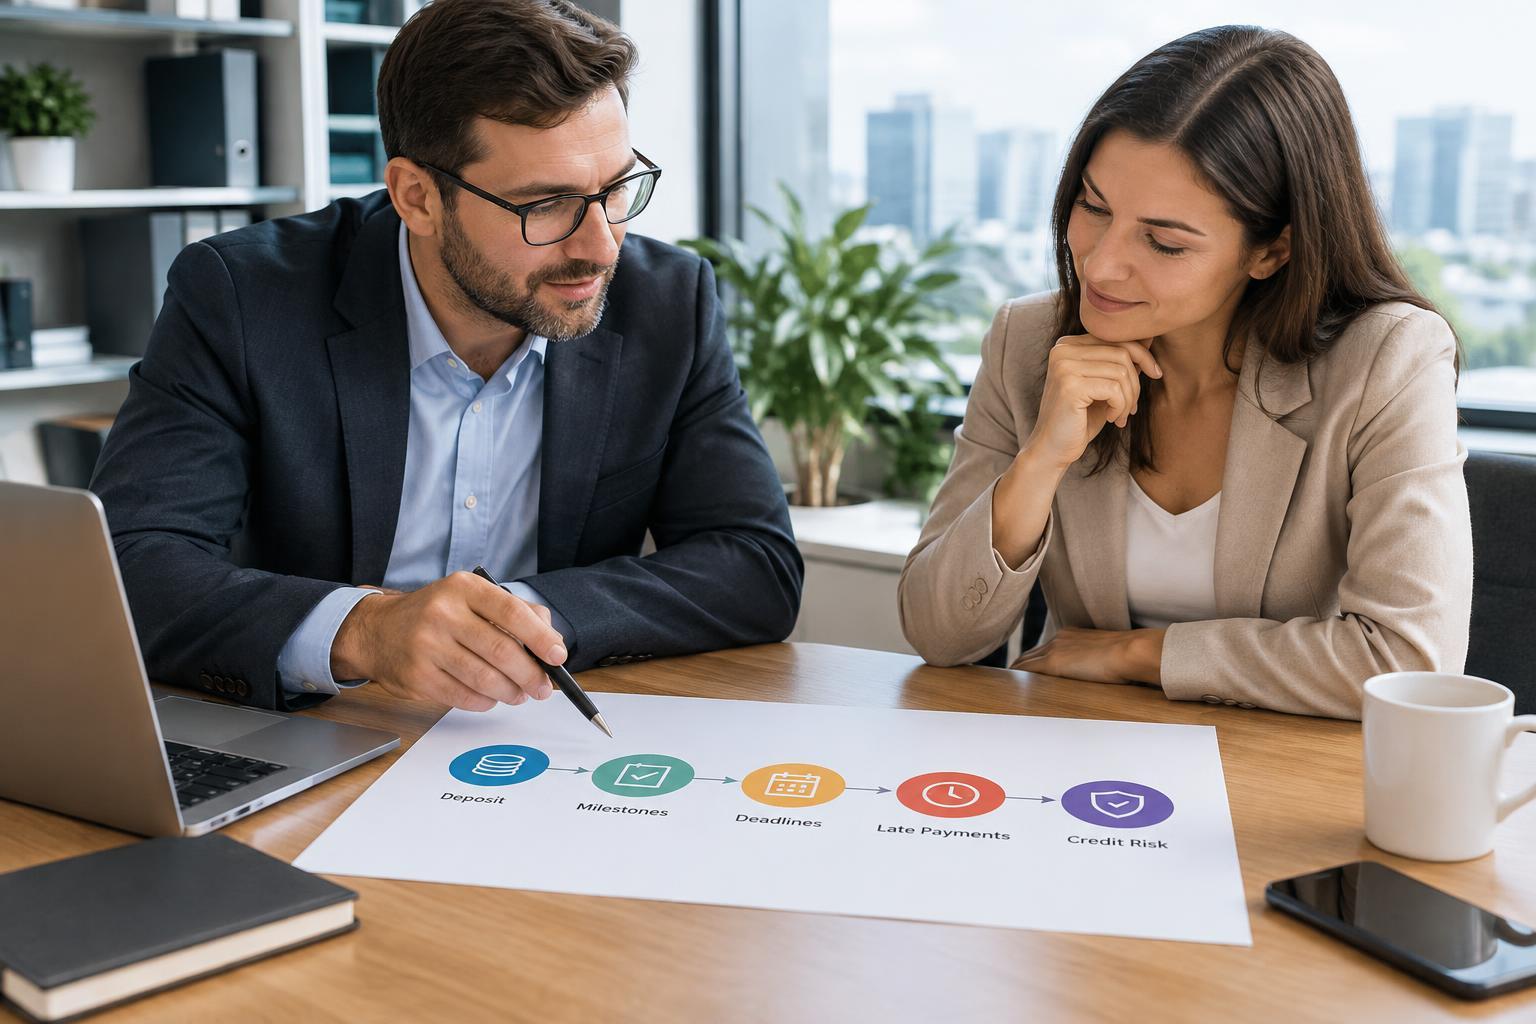
What B2B Payment Terms Actually Define
B2B payment terms are the agreed rules governing how one business pays another. They cover more than the number of days printed on an invoice: they can specify deposits, billing events, payment methods, currencies, approval requirements, and the process for resolving disputed charges. Together, these details shape how much work a supplier completes before receiving cash.
The central trade-off is timing. Buyers often prefer to pay after delivery or acceptance, while suppliers need to cover labor, materials, and operating costs earlier. Neither advance payment nor extended terms are automatically appropriate for every relationship. The arrangement should reflect the work, its duration, the parties’ processes, and the amount of unpaid exposure involved.
Consistency matters across the quotation, order, agreement, and invoice. If one document says payment is due after delivery and another says after acceptance, both teams may follow different schedules. Resolving those differences before work begins helps prevent avoidable collection problems.
Deposits: Sharing the Upfront Commitment
A deposit is a payment collected before some or all of the work takes place. It can help cover setup activities, reserved capacity, or materials purchased for a particular customer. For customized work that cannot easily be resold, a deposit also reduces the supplier’s exposure if the buyer cancels or stops responding.
The important operational question is what the deposit covers. Documents should explain whether it is credited against the final invoice or another billing stage, when the remaining balance becomes due, and how changes or cancellations are handled. Calling a payment a deposit does not, by itself, settle whether it can be refunded; applicable rules and the agreement matter.
Advance payments also create risk for buyers because money leaves their business before delivery. Clear deliverables, realistic schedules, and smaller staged commitments can help both parties understand what they are exchanging. The objective is to make the upfront commitment visible, not simply shift every risk to the customer.
Milestone Billing: Connecting Payment to Progress
Milestone billing divides a project into defined stages, each associated with an invoice. A software implementation, for example, might have separate billing events for completed discovery, a configured test environment, and final handover. This can shorten the period during which a supplier funds an entire project without payment.
Effective milestones are observable. “Substantial progress” leaves room for disagreement, whereas delivery of named outputs gives both teams something concrete to review. Each stage should identify its deliverables, who reviews them, the review period, and how unmet requirements are reported. Acceptance-dependent billing can otherwise leave the invoice date uncertain.
Scope changes need an equally clear process. Additional work can alter the price, schedule, and billing events. Recording those changes before proceeding helps prevent a mismatch between what the delivery team builds and what the customer’s finance team expects to pay.
Invoice Deadlines: Make the Starting Point Explicit
Terms such as net 30 generally mean the full invoice amount is due within 30 days of a specified starting point. That starting point must be clear: it might be the invoice date, receipt of a valid invoice, or an agreed acceptance event. State whether the calculation uses calendar or business days and show the resulting due date where possible.
An accurate invoice can still stall if it misses the buyer’s administrative requirements. Before billing, confirm the correct legal entity, billing contact, purchase order requirements, submission channel, currency, and supporting documents. These checks reduce preventable rejections and help distinguish processing errors from genuine payment problems.
Also clarify the payment method and any agreed treatment of transfer charges. Independently verify unexpected bank-detail changes through a trusted contact method, rather than relying only on an email requesting the change.
Late Payments: Separate Delays from Disputes
An overdue invoice is a signal to investigate, not proof that a customer cannot pay. Common causes include missing documents, approval bottlenecks, disputed work, and cash constraints. A useful first follow-up confirms receipt, identifies the obstacle, and asks for a specific expected payment date.
Maintain a consistent escalation process: a reminder, direct contact with accounts payable, involvement of the commercial owner, and review of further unpaid work. Record explanations and promised dates so different teams do not send conflicting messages. Where practical and agreed, track disputed and undisputed amounts separately.
Late fees, interest, collection action, and service suspension may depend on the agreement and applicable law. Do not assume an invoice note makes them enforceable. Consequential steps warrant appropriate professional review rather than improvised threats.
Credit Risk: Look Beyond Overdue Invoices
Offering payment terms means accepting the possibility that payment arrives late or not at all. Exposure includes unpaid invoices, but it may also include unbilled work and customer-specific purchases. A customer can therefore remain within invoice deadlines while the supplier’s total commitment continues growing.
Operational controls can include reviewing payment history, verifying customer details, and setting internal thresholds for additional approval before exposure increases. New relationships provide less behavioral evidence than established ones. Repeated delays, broken payment promises, or rapidly expanding orders can justify a review, though none alone proves financial distress.
Track receivables by due date, customer, dispute status, and total exposure. Reliable reminders and escalation ownership matter as much as written terms. The goal is a repeatable payment process that supports sales without letting unclear obligations or unmanaged commitments accumulate.


